By David Akinmola
The National Insurance Commission (NAICOM) has warned insurance companies against keeping recapitalisation funds idle, urging them to deploy the capital to strengthen underwriting capacity, improve claims settlement and restore policyholders’ confidence.
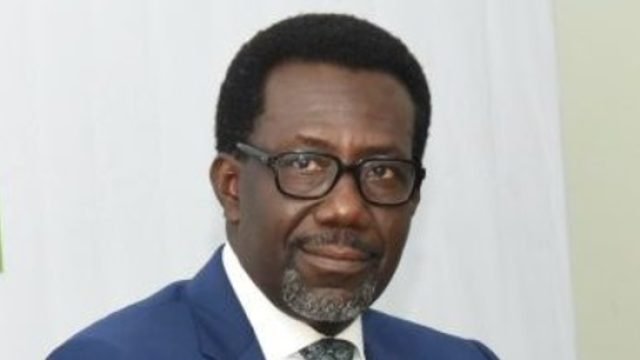
The Commissioner for Insurance, Olusegun Ayo Omosehin, gave the warning at the 2026 yearly industry conference in Lagos, stressing that compliance with the new minimum capital requirements would mean little if operators failed to deploy the funds productively to strengthen their businesses and improve service delivery.
“Capital should not remain idle on the balance sheet,” Omosehin said, insisting that the objective was not merely to have insurers raise additional funds, but to ensure that the capital worked to expand their capacity and strengthen the industry.
“We are not saying just bring it and keep it and just be looking at it and wake up and admire it every night. No, we want that capital to work and work for the industry,” he added.
The warning comes as the industry shifts attention from meeting the revised minimum capital requirements to demonstrating how stronger balance sheets can translate into greater risk-bearing capacity, improved claims payment and wider insurance coverage.
The regulator’s position highlights the need for insurers to move beyond compliance and build the technical expertise, risk assessment systems and financial resilience required to underwrite larger commercial transactions, infrastructure projects and industrial assets without weakening underwriting standards or exposing shareholders’ funds to excessive investment risks.
However, higher capital alone will not guarantee growth if operators continue to struggle with weak distribution networks, limited public confidence, poor product awareness and concerns over claims settlement.
Omosehin also called for disciplined investment policies anchored on capital preservation, liquidity and sustainable long-term returns, warning against excessive concentration of investments in volatile economic conditions. He said insurers must align their investments with their liabilities and maintain effective asset and liability management frameworks to ensure that funds remain available when claims fall due.
The commission is preparing the industry for a transition from the Minimum Capital Requirement framework to Risk-Based Capital supervision, under which capital adequacy will be assessed in relation to the risks undertaken by individual insurers. The proposed shift is expected to place greater emphasis on risk selection, solvency management and the quality of operators’ internal controls.
For insurers seeking to expand their portfolios, the transition will require stronger actuarial capabilities, improved risk modelling, sound investment decisions and closer board oversight of underwriting performance. Operators will need to demonstrate that their capital can absorb potential losses associated with the risks they accept, rather than rely solely on meeting regulatory thresholds.
The commissioner also identified prompt and complete settlement of genuine claims as a critical measure of the recapitalisation exercise’s success, warning that additional capital would have limited value if policyholders could not obtain the benefits due to them.
Claims payment remains central to efforts to rebuild public confidence and persuade more households, businesses and public institutions to use insurance as a dependable mechanism for managing financial risks. Persistent concerns over claims settlement, limited product awareness and weak distribution channels could undermine market expansion, even as insurers become better capitalised.
Omosehin further urged operators to strengthen corporate governance, transparency and accountability, particularly as new strategic investors enter the market. He called on boards and executive management teams to demonstrate ethical leadership, maintain regulatory compliance and ensure that capital is deployed in ways that support the long-term interests of policyholders and shareholders.
Digital distribution and technological innovation will also be important to widening access to insurance products, reducing distribution costs and reaching underserved segments of the population. The industry must equally address shortages of expertise in actuarial science, risk management, investment management and technology if recapitalised businesses are to remain sustainable.
The Nigerian Insurers Association (NIA), the umbrella body for insurance companies operating in the country, has also emphasised the importance of stronger underwriting capacity as the industry moves beyond recapitalisation.
The NIA Chairman, Ebelechukwu Nwachukwu, has said a well-capitalised insurance sector would be better positioned to honour obligations promptly, underwrite complex and large-scale risks, and support national economic growth.
Her position reflects the industry’s expectation that recapitalisation should enable insurers to take on risks that may previously have exceeded their financial capacity, including those associated with major infrastructure, industrial and commercial projects. However, achieving this will depend on sound risk selection, technical expertise, effective reinsurance arrangements and prudent investment management.
Ultimately, the success of the recapitalisation exercise will depend on whether the additional funds enable insurers to accept larger risks responsibly, settle legitimate claims promptly and expand coverage across the economy. For NAICOM, the priority is to ensure that capital is not merely available on paper but actively supports financially resilient businesses and delivers measurable value to policyholders.