By Emmanuel Enitan
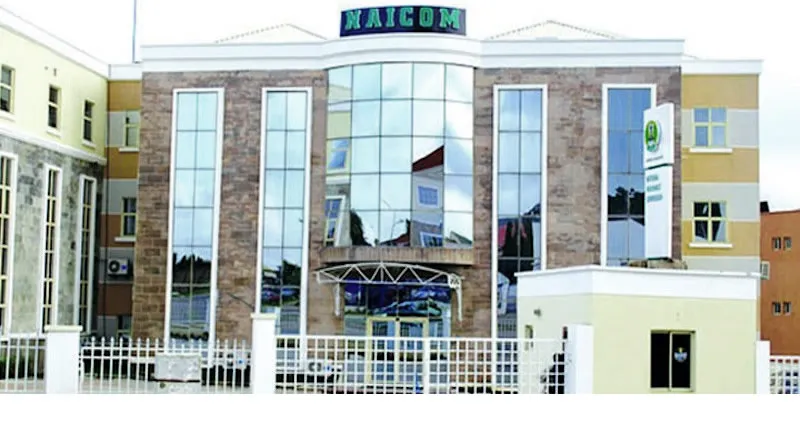
Nigeria’s insurance regulatory reforms are attracting regional interest, with Liberia seeking technical support from the National Insurance Commission (NAICOM) on risk-based capital requirements, supervisory practices and regulatory transitions as it moves to strengthen the financial resilience of its insurance industry.
The Central Bank of Liberia (CBL), which regulates the country’s insurance industry, made the request during a working visit to NAICOM by a delegation led by Mulbah Francis Bowah, identifying Nigeria’s experience as a potential guide for improving insurance supervision and strengthening regulatory institutions.
According to NAICOM, the Liberian delegation identified risk-based capital implementation, risk assessment and mitigation, insurance supervision and examination methodologies as priority areas for technical cooperation.
Bowah said Liberia was committed to strengthening its regulatory framework and expected Nigeria’s experience to support its ongoing reforms and the development of a more resilient insurance market.
He described Nigeria as a strategic partner in advancing insurance regulation across Africa, expressing appreciation for NAICOM’s willingness to share its experience and technical expertise.
The delegation was received by NAICOM’s Deputy Commissioner for Finance and Administration, Ekerete Ola Gam-Ikon, who represented the Commissioner for Insurance, Olusegun Ayo Omosehin.
Gam-Ikon reaffirmed the commission’s readiness to share regulatory experience and best practices with other African jurisdictions, highlighting the importance of regional cooperation, institutional capacity building and knowledge exchange in strengthening insurance supervision.
The engagement comes after Nigeria concluded its insurance industry recapitalisation exercise under the Nigerian Insurance Industry Reform Act (NIIRA) 2025, which introduced higher minimum capital requirements for insurance and reinsurance companies. NAICOM said 50 insurance and reinsurance companies had met the new capital requirements by the end of the compliance period on July 31, 2026.
Beyond recapitalisation, Nigeria’s experience holds potential lessons for Liberia on the relationship between capital adequacy, risk management and effective supervision. However, stronger capital requirements alone cannot guarantee a resilient insurance market without sound underwriting, effective corporate governance, reliable financial reporting and prompt settlement of legitimate claims.
From an industry perspective, the move towards risk-based capital supervision represents a shift from assessing insurers mainly against prescribed minimum capital thresholds to examining whether their capital is sufficient for the risks they undertake. Such a framework can encourage more disciplined underwriting and improve regulators’ ability to identify vulnerabilities before they threaten an insurer’s solvency.
For insurers, however, the transition can require substantial investment in actuarial expertise, risk modelling, data management and internal controls. Regulators must also develop the technical capacity to assess complex portfolios consistently and ensure that supervisory requirements reflect the realities of their domestic markets.
Liberia’s engagement with NAICOM therefore raises a broader question about how African insurance regulators can adapt international supervisory practices to local market conditions without imposing requirements that exceed the capacity of operators or supervisory institutions.
For Nigeria, sharing its experience provides an opportunity to deepen regulatory cooperation across the continent. It also places greater importance on demonstrating that its own reforms can deliver practical improvements in underwriting capacity, financial stability and consumer protection.
The ultimate test for both countries will be whether stronger supervisory frameworks translate into financially sound insurers, greater public confidence and more dependable protection for policyholders. Regional knowledge-sharing can support that process, but the effectiveness of reform will depend on implementation, enforcement and the willingness of operators to embrace stronger risk-management standards.